Down Payment Assistance in Texas: Programs Every New Buyer Should Know
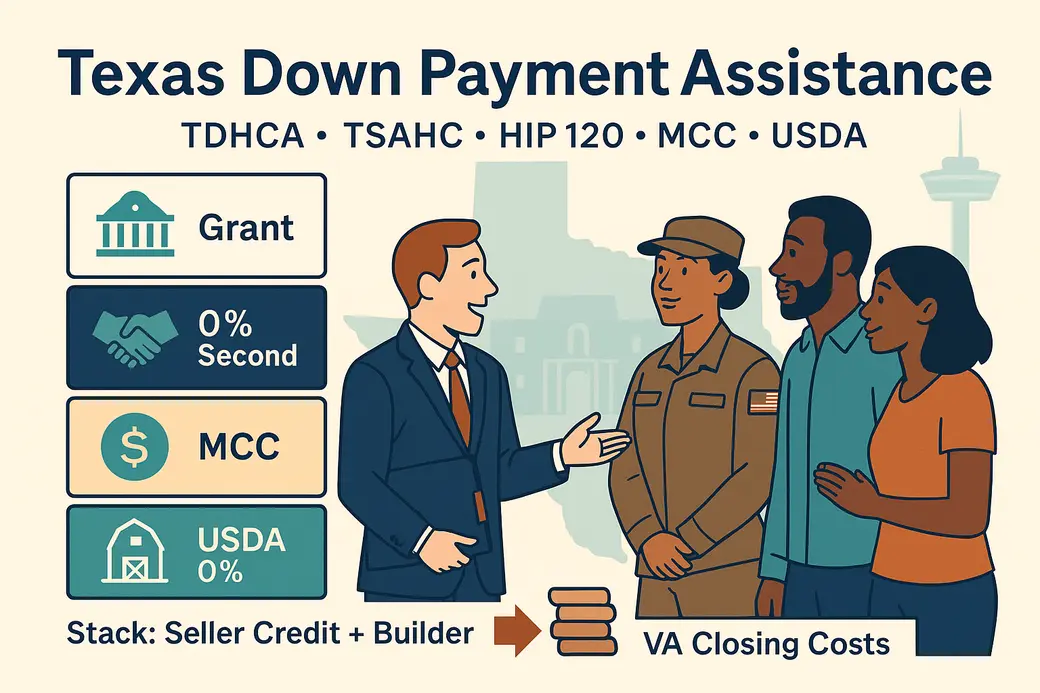
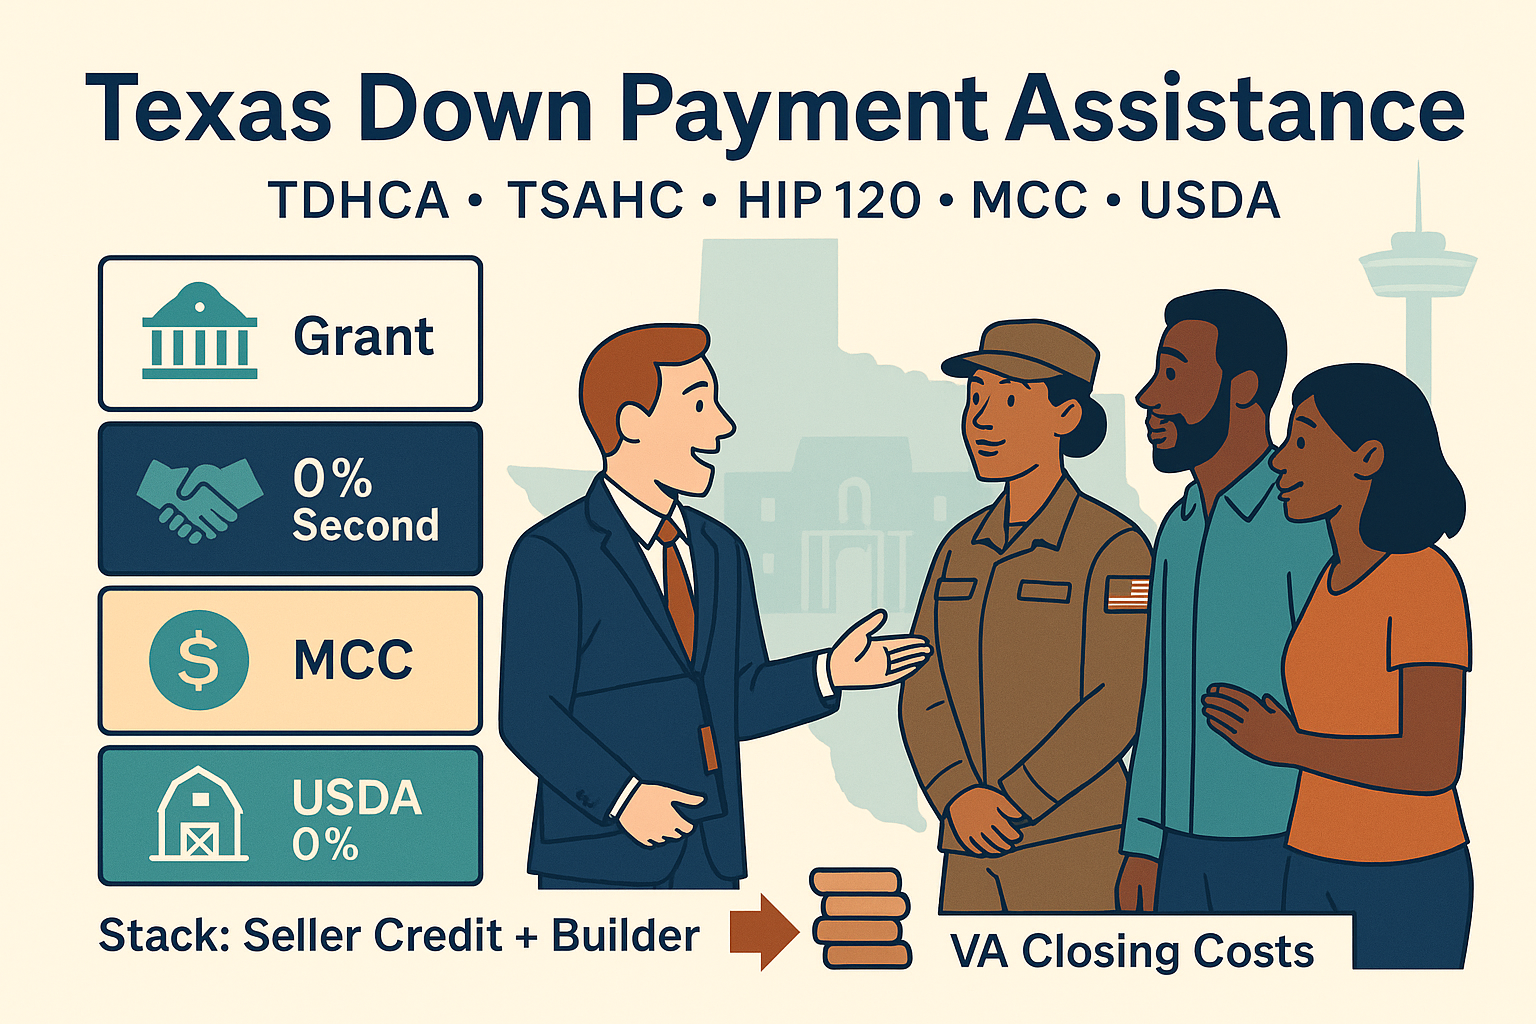 If saving for a down payment feels like the last big wall between you and the front door, this guide is your ladder. Whether you’re a first-time buyer, a military family PCSing to JBSA–San Antonio, or a renter finally ready to build equity, Texas offers several programs that can shrink your cash-to-close—often by thousands.
Below, I’ll break down the statewide programs (TDHCA & TSAHC), the San Antonio HIP 120 program, Mortgage Credit Certificates (MCCs), and USDA 0% down options. You’ll see who qualifies, how they work, and smart ways to stack credits with seller/builder incentives to lower your out-of-pocket costs.
🎯 Quick help: Want a customized “cash-to-close” plan for your price point and timeline? Book a free 15-minute DPA Strategy Call and I’ll map the best programs for you (including VA options if you’re eligible).
What “Down Payment Assistance” actually means (plain English)
“Down payment assistance” (DPA) can come as:
-
A grant (you don’t repay it), or
-
A second lien (a 0% interest loan—sometimes forgivable over time, sometimes due when you sell or refinance).
Most Texas buyers access DPA through approved lenders who originate your primary mortgage and layer eligible assistance on top. Program income and purchase price limits apply, and funds can be limited—so timing and pre-approval matter.
Who this guide is for
-
First-time buyers who need a lower cash-to-close
-
Military buyers (PCS to San Antonio) comparing VA zero-down with DPA to offset closing costs
-
Renters who want to convert monthly payments into equity sooner
-
Repeat buyers who don’t qualify as “first-time” but still want help (some programs allow it)
The big three advantages of using DPA
-
Lower out-of-pocket so you can buy sooner (or keep your emergency fund intact).
-
Negotiation leverage: when combined with builder/seller credits, you can trim total cash needs and sometimes your rate (via buydowns).
-
Confidence: a clear, pre-approved DPA plan helps you write stronger, cleaner offers.
Texas Statewide Programs (TDHCA & TSAHC)
1) TDHCA: My First Texas Home & My Choice Texas Home
What it is: The Texas Department of Housing & Community Affairs (TDHCA) operates the Texas Homebuyer Program, which includes:
-
My First Texas Home – for first-time buyers and veterans
-
My Choice Texas Home – for repeat buyers
Both pair a 30-year fixed-rate mortgage with down payment and/or closing cost assistance delivered by participating lenders. Texas Housing Departmenthrc-ic.tdhca.state.tx.us
Notes:
Amounts and formats (grant vs. repayable/forgivable seconds) vary by program and market conditions; your lender will show current options. TDHCA clearly indicates that programs are administered through participating lenders and that funding availability can change. hrc-ic.tdhca.state.tx.us
Who it helps most:
-
First-time buyers and veterans (My First)
-
Repeat buyers who still need help with cash-to-close (My Choice)
Why it’s powerful: It’s statewide, works with common loan types (FHA/VA/Conventional), and is already embedded with many Texas lenders—so the process is familiar and fast. Texas Housing Department
Pro tip for San Antonio buyers: If the property is new construction, ask about builder credits to stack with TDHCA—often the fastest way to slash prepaid items and total cash due at closing.
2) TSAHC: Loans, DPA & “Homes for Texas Heroes”
The Texas State Affordable Housing Corporation (TSAHC) is a statewide nonprofit created by the Legislature. TSAHC provides 30-year fixed loans, down payment assistance (grant or second-lien options), and Mortgage Credit Certificates (more on MCCs below). Texas Housing Corp+1
Programs to know:
-
Home Sweet Texas – for qualifying homebuyers statewide
-
Homes for Texas Heroes – for teachers, firefighters/EMS, police/corrections and veterans (great for military families). Texas Housing Corp
Key advantages:
-
Grant or forgivable/repayable second options to help with down payment and closing costs
-
Statewide availability via approved lenders (easy to find and price) Texas Housing Corp
MCC combination: TSAHC confirms you can combine its Mortgage Credit Certificate (MCC) with TSAHC DPA, and as of mid-2025, the stand-alone MCC option is discontinued—meaning MCCs are paired with TSAHC’s DPA/0% options. (Your lender will check current status when you apply.) kb.tsahc.org
San Antonio Spotlight: HIP 120 (City of San Antonio)
If you’re buying inside San Antonio city limits, the Homeownership Incentive Program (HIP 120) can be a game changer.
How it works (at a glance):
-
$1,000–$15,000 as a 0% interest, no-payment second lien to cover required down payment and some closing costs
-
75% of the loan is forgiven over 10 years; 25% remains a 0% “perpetual” loan due at sale, refinance, or transfer
-
Must be first-time homebuyer, within income limits, and purchase within city limits
-
Compatible with FHA, VA, or Conventional first mortgages (no owner financing) 311 San AntonioSan Antonio+1
This structure (part forgivable, part perpetual) is designed to keep homes affordable while recycling funds when owners sell/refi—so read the terms and plan your timeline.
Mortgage Credit Certificates (MCC): The tax credit most buyers miss
An MCC is not cash at closing. It’s a federal income tax credit you can claim every year on a portion of your mortgage interest (subject to IRS rules). TSAHC’s published materials explain the credit calculation and provide examples (e.g., 20% of annual mortgage interest as the credit in their example). This reduces your tax liability dollar-for-dollar and can improve monthly affordability if you adjust withholding. kb.tsahc.org
Why it matters: The MCC can be worth thousands over the life of the loan and often pairs with DPA, improving both upfront and long-term affordability. TSAHC notes the MCC is paired with its DPA/0% options (see note above). kb.tsahc.org
Bonus: USDA 0% Down (for eligible areas)
Outside major metro cores, the USDA Single Family Housing Guaranteed Loan offers 100% financing (no down payment) for eligible buyers and properties in USDA-eligible rural areas. Income and location rules apply; your lender can check an address instantly. Rural Development+1
If you’re relocating to the San Antonio region, some outer-ring communities may qualify. USDA + seller/builder credits can mean very low cash-to-close.
Can VA buyers use down payment assistance?
If you’re VA-eligible, your down payment can be 0%—but you still have closing costs and prepaids. Certain local/state DPA programs (including San Antonio HIP 120) indicate compatibility with VA first mortgages, subject to program rules and lender overlays. Always have your lender verify current guidelines and fund availability. San Antonio
How to choose the right program (simple 5-step path)
-
Get pre-approved with a Texas-savvy lender who actively closes TDHCA/TSAHC/HIP files. Ask for scenarios that compare no-assistance vs. assistance on the same property.
-
Check eligibility (income, purchase price, location, first-time status). Your lender uses current program sheets and calculates total cash-to-close precisely.
-
Decide on DPA format: Grant (no repayment) vs. forgivable second vs. repayable second. We’ll weigh the rate trade-off (sometimes grants carry slightly higher rates).
-
Consider stacking: Add MCC (if available) and seller/builder credits to reduce both upfront costs and monthly payment (via buydowns or PMI/MIP impacts). kb.tsahc.org
-
Pick the path that balances: lowest cash-to-close, manageable payment, and resale plan (some programs have occupancy/time requirements).
Real-life examples
A) First-time renter in San Antonio (FHA + HIP 120 + builder credit)
-
Profile: Teacher renting near JBSA; modest savings; wants a low-maintenance new build.
-
Plan: FHA loan + HIP 120 second lien + builder credit toward closing.
-
Outcome: HIP covered part of down payment/closing; builder credit handled prepaids; closed with under $5,000 total cash and set a plan to apply for homestead and refinance if rates drop. 311 San Antonio
B) Military family PCSing to JBSA (VA + TSAHC DPA + MCC)
-
Profile: E-6 with dependents; strong BAH; needs to preserve savings for the move.
-
Plan: VA first mortgage (0% down) + TSAHC DPA for closing costs + MCC for ongoing tax savings.
-
Outcome: Out-of-pocket limited to earnest/inspections; the MCC improved annual cash flow and helped qualify comfortably on the BAH budget. Texas Housing Corpkb.tsahc.org
C) Repeat buyer moving within Texas (Conventional + TDHCA “My Choice”)
-
Profile: Sold prior home, but netted less cash than expected; wants to keep reserves.
-
Plan: Conventional loan with My Choice Texas Home assistance to offset cash-to-close.
-
Outcome: Closed with an emergency fund still intact and a payment aligned to income. Texas Housing Department
Program cheat sheet (save this)
TDHCA – Texas Homebuyer Program
-
My First Texas Home (first-timers & veterans)
-
My Choice Texas Home (repeat buyers)
-
30-year fixed loans + DPA/closing cost help via participating lenders (amounts vary; funding can change). Texas Housing Departmenthrc-ic.tdhca.state.tx.us
TSAHC
-
Home Sweet Texas & Homes for Texas Heroes (includes veterans)
-
DPA as grant or second lien + available MCC tax credit; offered through approved lenders. Texas Housing Corp+1
San Antonio HIP 120
-
City-limit purchases, income limits apply
-
0% second lien, 75% forgiven over 10 years, 25% perpetual due at sale/refi/transfer; compatible with FHA/VA/Conventional. San Antonio+1
USDA (rural areas)
-
0% down in eligible locations for qualifying incomes; check addresses with your lender. Rural Development
Frequently asked questions
Will DPA raise my interest rate?
Sometimes. Certain grant options may have a slightly higher rate than standard loans; forgivable or repayable seconds can price differently. That’s why we run side-by-side quotes on the same home so you can see the real trade-offs.
Can I combine DPA with a seller or builder credit?
Yes—often the best way to bring cash-to-close near zero is to stack program assistance with seller/builder contributions, applied to prepaids, rate buydowns, or closing costs (subject to loan program caps).
Do MCCs help at closing?
Not directly. An MCC is a tax credit on a percentage of mortgage interest each year; it helps after closing (you can adjust payroll withholding to feel it monthly). TSAHC provides MCC guidance and examples. kb.tsahc.org
I’m VA-eligible. Should I still look at DPA?
If you want to reduce closing costs/prepaids, yes. Programs like HIP 120 indicate VA compatibility; your lender will verify current terms. San Antonio
How do I know which program is funded right now?
Funding cycles change. TDHCA and TSAHC both operate through approved lenders who can confirm real-time availability and lock your reservation once you’re under contract. hrc-ic.tdhca.state.tx.us
Your 30-Day Action Plan
Week 1 – Numbers & eligibility
-
Get pre-approved and ask your lender to price:
-
No assistance, 2) TDHCA scenario, 3) TSAHC scenario (with MCC if available), 4) HIP 120 (if buying inside San Antonio city limits).
-
-
If VA-eligible, include a VA + DPA for closing costs scenario. San Antonio
Week 2 – Paperwork & education
-
Upload paystubs/W-2/LES (military), bank statements, gift letters if any.
-
Complete any required homebuyer education early (some programs require it).
Week 3 – Market strategy
-
Identify neighborhoods that fit your payment cap (we’ll factor taxes, HOA, insurance).
-
If considering new construction, request current builder incentives to stack with DPA.
Week 4 – Offer readiness
-
Build your clean-offer strategy (option period, timelines, appraisal plan).
-
Ask me for a negotiation checklist that targets seller credits without weakening your offer.
Strong Calls to Action (pick your path)
-
Book a 15-minute DPA Strategy Call. I’ll run your cash-to-close numbers across TDHCA, TSAHC (with MCC), HIP 120, and (if eligible) VA/USDA.
-
Want the free PDF? Reply “DPA CHECKLIST” and I’ll send a printable Down Payment Assistance Checklist + Questions for Your Lender.
-
Need lender intros? I’ll connect you with Texas-savvy lenders who close TDHCA/TSAHC/HIP files every month and understand PCS timelines.
Categories
- All Blogs (324)
- Agent (46)
- Buydown (1)
- buying tips (78)
- Case Study (2)
- Divorce (1)
- Events (1)
- first time home buyer (51)
- First-Time Landlord (1)
- Halloween (1)
- home for sale (98)
- Home Rental (11)
- Homeowners (8)
- Interest Rate (2)
- Investment (23)
- Lifestyle & Community Guide (101)
- Market Trend (14)
- Mindset (1)
- Mortgage (7)
- New Braunfels (1)
- New Braunfels Lifestyle (57)
- Outdoor (1)
- Preventive Home Maintenance (4)
- Property Taxes, (17)
- Real Estate (229)
- Real Estate Market (10)
- Realtors (97)
- Savings (2)
- Settlement (1)
- Solar Panels (1)
- Summer in New Braunfels, (1)
- Veterans (4)
Recent Posts
GET MORE INFORMATION