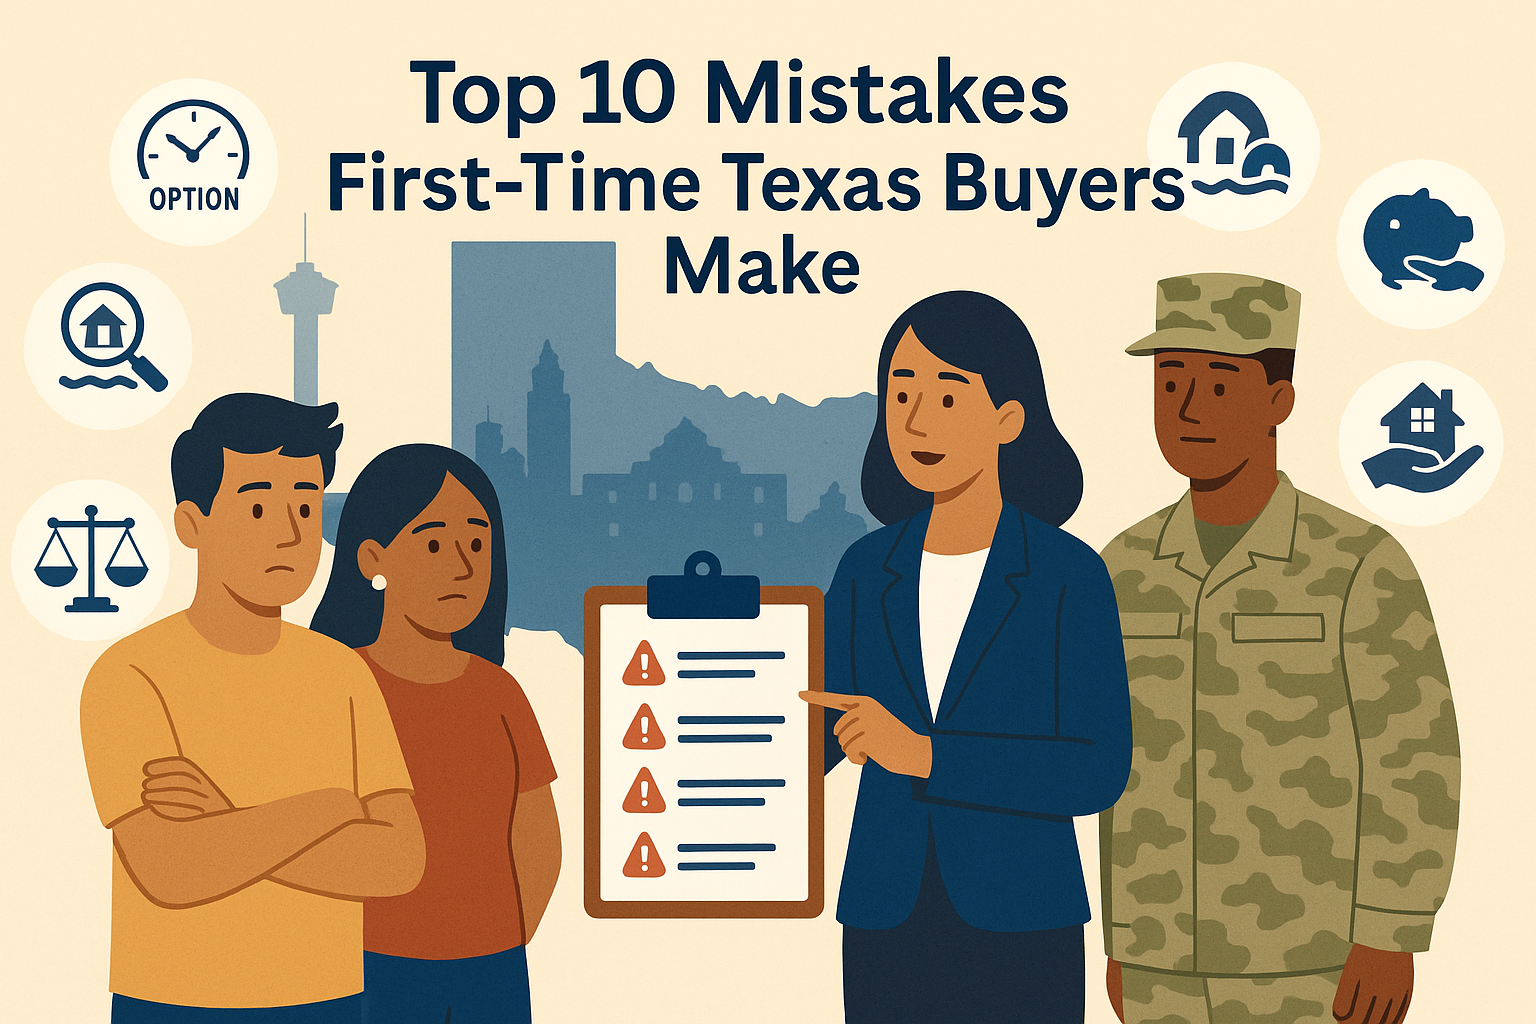
Top 10 Mistakes First-Time Texas Buyers Make (and How to Avoid Them)
 Buying your first home in Texas is exciting—until it’s… a lot. Contracts with new-to-you clauses, flood maps, appraisals, “option periods,” and that never-ending list of documents your lender needs. As an agent who works closely with first-time buyers, military families relocating to San Antonio (JBSA), and renters transitioning into homeownership, I see the same avoidable mistakes that can derail timelines and cost thousands.
Below are the 10 most common pitfalls—and exactly how to dodge them—so you can move from “I think we’re ready” to “we’ve got the keys” with confidence.
👋 Want a quick, customized game plan? Book a free 15-minute Buyer Strategy Call and I’ll map your budget, loan fit, and a neighborhood shortlist around your commute.
1) Shopping before you know your numbers
The mistake: Browsing listings and touring homes without a full pre-approval. You fall in love with a house, then learn the payment or cash-to-close doesn’t work—or that a different loan type would save you more.
Fix it:
-
Get a true pre-approval (not just a quick pre-qual).
-
Price out two to three loan scenarios (e.g., Conventional 3–5% down, FHA 3.5%, VA 0% for eligible buyers).
-
Include taxes, insurance, and HOA in payment estimates—Texas property taxes vary by area and can move the needle.
Military tip: If you’re VA-eligible, confirm your eligibility and compare the VA scenario; VA loans commonly offer no down payment and no monthly mortgage insurance, which can materially lower your monthly payment. Benefits
CTA: Want me to run an apples-to-apples cost comparison for your price range? Message me your target payment and I’ll send a side-by-side.
2) Confusing the option period with “just a free look”
The mistake: Treating the option period like a casual hold or assuming it’s guaranteed even if fees aren’t delivered correctly.
Fix it: In Texas, the termination option is a negotiated window that gives buyers the unrestricted right to terminate for any reason if they follow the contract terms. It exists to reduce post-closing disputes and lets you complete inspections and due diligence. Texas Real Estate Research Center
Two keys many first-timers miss:
-
Delivery of the option fee now goes to the title company (not the seller) under the updated TREC contracts, and timing rules apply. TREC
-
If the option fee isn’t paid as the contract requires, you may lose the right to terminate under the option. TREC
Pro move: We’ll structure your calendar—inspections, quotes, estimates—so you’re never bumping up against your deadline.
3) Skipping the inspection because there’s an appraisal
The mistake: Assuming an appraisal = inspection or that your lender will “catch” condition issues.
Fix it: An appraisal is an independent estimate of value that your lender orders; an inspection studies the condition of the home. Lenders typically require appraisals but not inspections—yet skipping an inspection can lead to costly surprises. Consumer Financial Protection Bureau
What we do: We schedule inspections early in the option period, then use findings to negotiate repairs or credits when appropriate.
4) Ignoring flood risk until insurance quotes land
The mistake: Only checking floods after you’re in escrow—then discovering premiums you didn’t budget for or lender requirements you must meet.
Fix it: Check flood risk before you offer using FEMA’s Flood Map Service Center and talk to your insurance pro about likely costs. Some properties outside high-risk zones still flood; get clarity upfront. FEMA Flood Map Service Center
Military PCS tip: If you’re on a tight timeline, we’ll screen listings for floodplain flags before showings to avoid last-minute surprises.
5) Overlooking down payment assistance you actually qualify for
The mistake: Believing assistance is only for very low incomes or only for FHA loans.
Fix it: Texas has multiple options that can pair with Conventional, FHA, and even VA in many cases. Programs update frequently, but two reliable places to start are:
-
TDHCA (Texas Department of Housing & Community Affairs) – State program that offers homebuyer education, down payment, and closing cost assistance through approved lenders. The Texas Homebuyers Program
-
TSAHC (Texas State Affordable Housing Corporation) – Loans + Down Payment Assistance (grants or second liens) and a Homes for Texas Heroes program that includes veterans (along with other professions). TSAHC+1
How I help: I coordinate with lenders who actively work these programs, so you know exactly how much cash you need and where credits can offset your costs.
6) Forgetting about the Texas Homestead Exemption
The mistake: Closing on your primary residence and never filing for homestead, leaving tax savings on the table.
Fix it: File your homestead exemption with your county appraisal district after you buy. The general filing deadline is before May 1 for that tax year (with some late-filing provisions). Texas Comptroller
After closing the checklist, I will send you: the Homestead application link for your county, how to set up escrow reviews, and reminders for property tax protests when it makes sense.
7) Writing offers that don’t match the market
The mistake: Using a one-size-fits-all offer template. Sometimes you overpay; other times you make a weak offer and lose the home you love.
Fix it: We tailor strategy to the micro-market (neighborhood + price band):
-
In competitive pockets, we favor clean terms and communication that builds seller confidence.
-
Where days-on-market are longer (or on new construction), we target seller credits to lower your cash-to-close or rate buydowns.
-
If you’re VA, we position your financing clearly and select homes with strong comps to avoid appraisal friction.
CTA: Ask me for a comp set + offer template for your target neighborhood before you write.
8) Not planning for post-closing cash flow
The mistake: Using every dollar to close—then feeling strapped the first six months because you didn’t plan for utilities, maintenance, or HOA special assessments.
Fix it:
-
Keep a home maintenance fund (1–2% of purchase price per year).
-
Confirm insurance (wind/hail, flood if needed) and utilities for a true monthly number.
-
If you’re VA/PCS, align your budget with BAH and practice the payment now by moving the difference from today’s rent into savings each month.
9) Failing to prepare for appraisal outcomes
The mistake: Assuming the value will always meet the contract price or not preparing a plan if it comes in low.
Fix it: Appraisals are lender-ordered valuations that influence your loan size and terms. We discuss options before we offer—like reconsideration of value, price adjustments, or additional cash—so you’re never blindsided by a valuation hiccup. Consumer Financial Protection Bureau
Pro move: We choose comps strategically and, when appropriate, share relevant data through the lender to help the appraiser see the full picture.
10) Going it alone (or with the wrong team)
The mistake: Hiring the first agent or lender you find—or trying to self-navigate. In Texas, the learning curve is real: option periods, addenda, title policy, HOA docs, surveys, flood maps, and assistance programs all interact.
Fix it: Work with a Texas-savvy agent and a lender who closes VA, FHA, and assistance files every month, not once a year. This shrinks your timeline and lowers your stress.
✅ Need vetted intros? I’ll connect you with local lenders who know VA and Texas programs cold and can move quickly on PCS timelines.
Quick Reference: Texas Concepts You’ll Hear (and Why They Matter)
-
Option Period / Termination Option – A negotiated window for due diligence; if exercised properly and on time, you can terminate for any reason. Delivery and timing of the option fee (to the title company) are governed by updated TREC forms. Texas Real Estate Research CenterTREC
-
Appraisal vs. Inspection – Appraisal = value (lender-ordered). Inspection = condition (buyer-ordered). Appraisal is typically required; inspection usually isn’t—but skipping it is risky. Consumer Financial Protection Bureau
-
VA Loan – For eligible service members/veterans; often no down payment and no monthly mortgage insurance. Great for JBSA buyers. Benefits
-
Down Payment Assistance – TDHCA and TSAHC are state-level starting points; local city programs may also help. We’ll check current eligibility and funding. The Texas Homebuyers ProgramTSAHC
-
Homestead Exemption – Tax savings on your primary residence; generally file before May 1 with your county appraisal district. Texas Comptroller
-
Flood Risk – Check FEMA’s Map Service Center early and get quotes; some “low-risk” areas still flood. FEMA Flood Map Service Center
A short success story: PCS to keys in 30 days
A sergeant with dependents received orders to JBSA and needed housing fast. We:
-
Pre-approved with a VA lender and created a payment cap anchored to BAH.
-
Screened neighborhoods by commute and schools, removing flood-zone headaches early using FEMA maps. FEMA Flood Map Service Center
-
Found a home with strong comps; the builder covered a portion of the closing costs.
-
Cleared the option period quickly with an efficient inspection schedule.
-
Closed on time with $0 down and a payment aligned to BAH. Benefits
Result: Smooth move-in, no surprise expenses, and tax savings queued up with the homestead filing. Texas Comptroller
Your 5-Step “No-Regrets” Plan
-
Get pre-approved and ask for a multi-scenario cost breakdown (VA/FHA/Conventional).
-
Book inspections the day your contract is executed; don’t wait.
-
Check FEMA flood maps and get insurance quotes before you offer in certain areas. FEMA Flood Map Service Center
-
Use assistance where it fits (TDHCA/TSAHC + any local programs). The Texas Homebuyers ProgramTSAHC
-
File the homestead after closing and set a reminder for any county deadlines. Texas Comptroller
Strong Calls to Action (Pick your path)
-
Schedule a 15-minute Buyer Strategy Call. I’ll map your budget, loan fit, and a neighborhood list around your commute (JBSA, Lackland, Fort Sam, Randolph).
-
Ask for a lender intro. I’ll connect you with Texas lenders fluent in VA + assistance to cut your cash-to-close.
-
Get my free PDF: “First-Time Texas Buyer Kit”—offer templates, option period checklist, and a homestead filing guide.
Categories
- All Blogs (324)
- Agent (46)
- Buydown (1)
- buying tips (78)
- Case Study (2)
- Divorce (1)
- Events (1)
- first time home buyer (51)
- First-Time Landlord (1)
- Halloween (1)
- home for sale (98)
- Home Rental (11)
- Homeowners (8)
- Interest Rate (2)
- Investment (23)
- Lifestyle & Community Guide (101)
- Market Trend (14)
- Mindset (1)
- Mortgage (7)
- New Braunfels (1)
- New Braunfels Lifestyle (57)
- Outdoor (1)
- Preventive Home Maintenance (4)
- Property Taxes, (17)
- Real Estate (229)
- Real Estate Market (10)
- Realtors (97)
- Savings (2)
- Settlement (1)
- Solar Panels (1)
- Summer in New Braunfels, (1)
- Veterans (4)
Recent Posts
GET MORE INFORMATION