Why More Self-Employed Buyers Are Using Bank Statement Loans
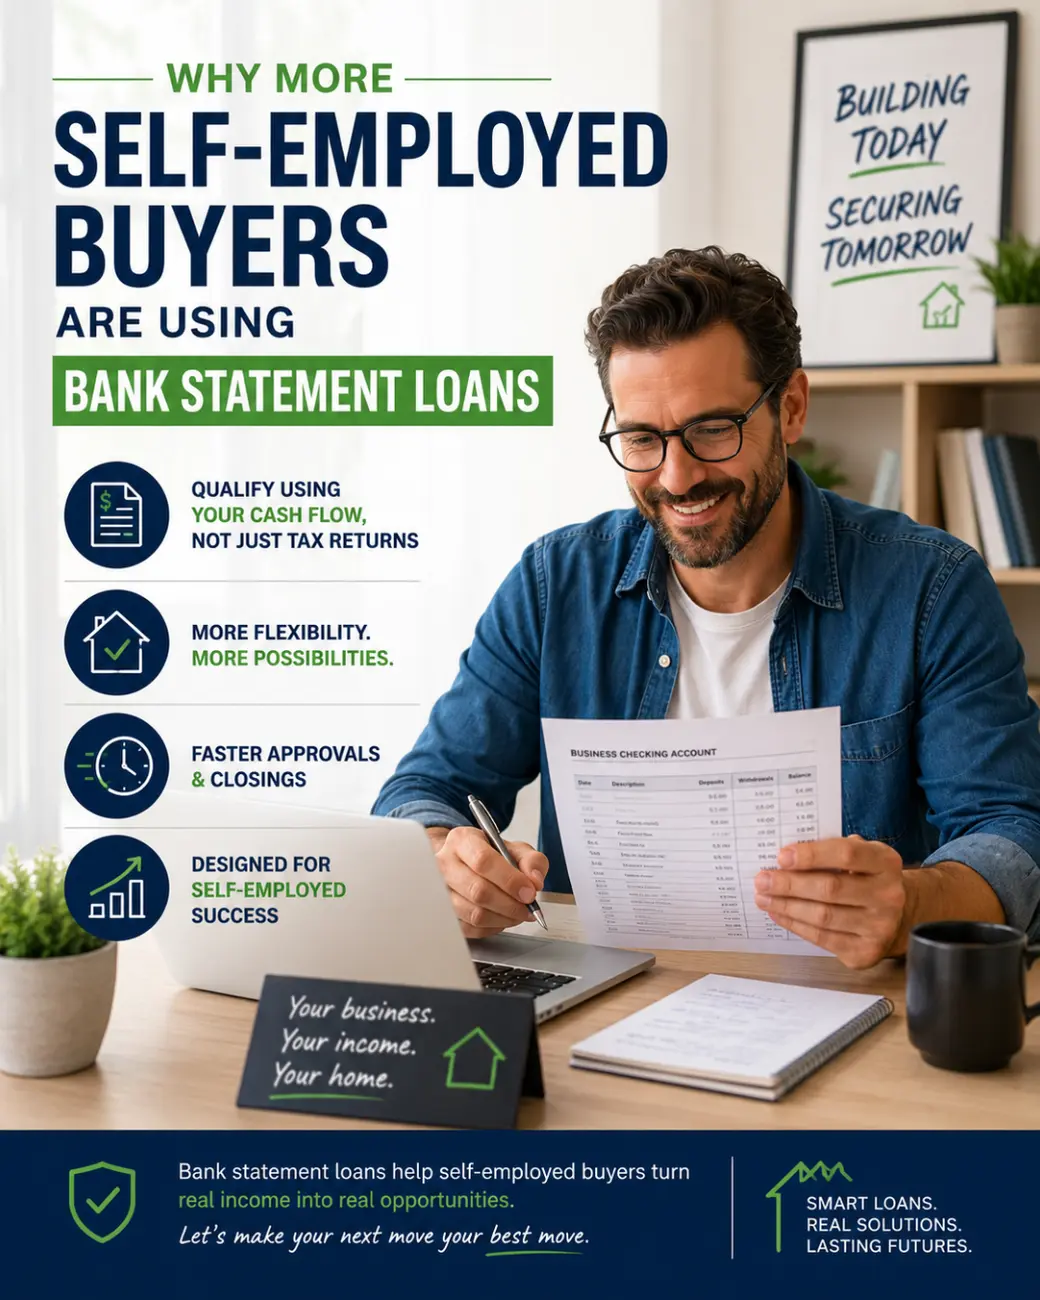
Why More Self-Employed Buyers Are Using Bank Statement Loans
The traditional path to getting a mortgage works well for many homebuyers, but it doesn't always reflect how today's entrepreneurs and self-employed professionals earn a living. Small business owners, freelancers, consultants, independent contractors, and content creators often have strong cash flow but don't fit neatly into conventional lending guidelines.
That's one reason bank statement loans have become an increasingly popular financing option for qualified self-employed borrowers. These loan programs offer an alternative way to document income, making homeownership more accessible for buyers whose finances look different from a traditional W-2 employee's.
If you're planning to buy a home in New Braunfels, Canyon Lake, or the surrounding Texas Hill Country, here's what you should know about bank statement loans and why they're gaining attention.
What Is a Bank Statement Loan?
A bank statement loan is a type of mortgage that allows eligible self-employed borrowers to verify income using bank statements rather than relying primarily on W-2s or tax returns.
Because many entrepreneurs claim legitimate business deductions that reduce their taxable income, tax returns may not always reflect the full financial picture of a successful business. Bank statement loans give lenders another way to evaluate a borrower's ability to repay a mortgage.
While these loans are commonly associated with non-qualified mortgage (non-QM) programs, they are offered by participating lenders under their own underwriting guidelines. Program features and eligibility requirements vary.
Who May Benefit from a Bank Statement Loan?
Bank statement loans are often considered by borrowers such as:
- Small business owners
- Entrepreneurs
- Freelancers
- Independent contractors
- Consultants
- Real estate professionals
- Commission-based sales professionals
- Content creators and influencers
- Gig economy workers
These borrowers may earn consistent income without receiving a traditional W-2 paycheck.
Why Traditional Mortgages Can Be Challenging
Many self-employed professionals invest heavily in their businesses and use legitimate tax deductions to reduce taxable income.
Examples of deductible expenses may include:
- Equipment purchases
- Business travel
- Office expenses
- Vehicle expenses
- Marketing costs
- Professional services
While these deductions can reduce taxes, they may also lower the income reflected on tax returns, which can affect qualification under conventional mortgage guidelines.
A bank statement loan may provide an alternative documentation path for eligible borrowers.
How Do Bank Statement Loans Work?
Although every lender has different requirements, bank statement loans generally involve reviewing a series of personal or business bank statements to evaluate cash flow and income patterns.
Lenders may consider factors such as:
- Deposit history
- Income consistency
- Business expenses
- Length of self-employment
- Credit history
- Available assets
- Debt obligations
The exact documentation required depends on the lender and the specific loan program.
Advantages of Bank Statement Loans
For the right borrower, bank statement loans can offer several benefits.
More Flexible Income Documentation
Instead of relying solely on tax returns, lenders can evaluate your financial picture using bank deposits and other supporting documentation.
Designed for Self-Employed Borrowers
These programs recognize that entrepreneurs often have income structures that differ from traditional employees.
May Increase Purchasing Opportunities
Some borrowers who don't qualify under conventional documentation guidelines may find that an alternative documentation program better reflects their financial situation.
Qualification always depends on the lender's underwriting standards and the borrower's overall financial profile.
What Lenders Still Evaluate
Even though income documentation differs, lenders continue to review many of the same financial factors.
These often include:
- Credit score and credit history
- Down payment
- Debt-to-income considerations
- Cash reserves
- Property type
- Loan amount
- Overall financial stability
A bank statement loan is not a shortcut to mortgage approval. Borrowers are still expected to demonstrate the ability to repay the loan.
How to Prepare Before Applying
If you think a bank statement loan may fit your situation, preparation can make the application process smoother.
Before applying:
- Organize your bank statements.
- Keep business and personal finances well documented.
- Review your credit report.
- Avoid taking on significant new debt.
- Minimize large undocumented deposits.
- Speak with an experienced mortgage professional.
Getting pre-qualified or pre-approved early can also help you understand your financing options before you begin shopping for a home.
Frequently Asked Questions
Are bank statement loans only for business owners?
No. They are commonly used by eligible self-employed borrowers, including freelancers, consultants, contractors, and others with non-traditional income sources.
Do bank statement loans require tax returns?
Requirements vary by lender and loan program. Some programs focus primarily on bank statements while still requesting additional financial documentation.
Are bank statement loans available for primary residences?
Some lenders offer these programs for primary residences, while others may also finance second homes or investment properties. Availability depends on the lender and loan guidelines.
Should I compare multiple mortgage options?
Yes. A qualified mortgage professional can help you compare conventional financing with alternative documentation programs to determine which option best fits your financial goals.
Final Thoughts
As more professionals choose entrepreneurship, freelancing, and independent contracting, mortgage options have evolved to reflect today's workforce. Bank statement loans have become a valuable financing solution for eligible self-employed buyers whose income isn't accurately represented by traditional tax documents.
The most important step is working with an experienced lender who understands self-employed borrowers and can explain which mortgage programs may be appropriate for your financial situation.
If you're planning to purchase a home in New Braunfels, Canyon Lake, or the surrounding Texas Hill Country, exploring your financing options early can help you move through the buying process with confidence and focus on finding the right home.
Categories
- All Blogs (324)
- Agent (46)
- Buydown (1)
- buying tips (78)
- Case Study (2)
- Divorce (1)
- Events (1)
- first time home buyer (51)
- First-Time Landlord (1)
- Halloween (1)
- home for sale (98)
- Home Rental (11)
- Homeowners (8)
- Interest Rate (2)
- Investment (23)
- Lifestyle & Community Guide (101)
- Market Trend (14)
- Mindset (1)
- Mortgage (7)
- New Braunfels (1)
- New Braunfels Lifestyle (57)
- Outdoor (1)
- Preventive Home Maintenance (4)
- Property Taxes, (17)
- Real Estate (229)
- Real Estate Market (10)
- Realtors (97)
- Savings (2)
- Settlement (1)
- Solar Panels (1)
- Summer in New Braunfels, (1)
- Veterans (4)
Recent Posts
GET MORE INFORMATION